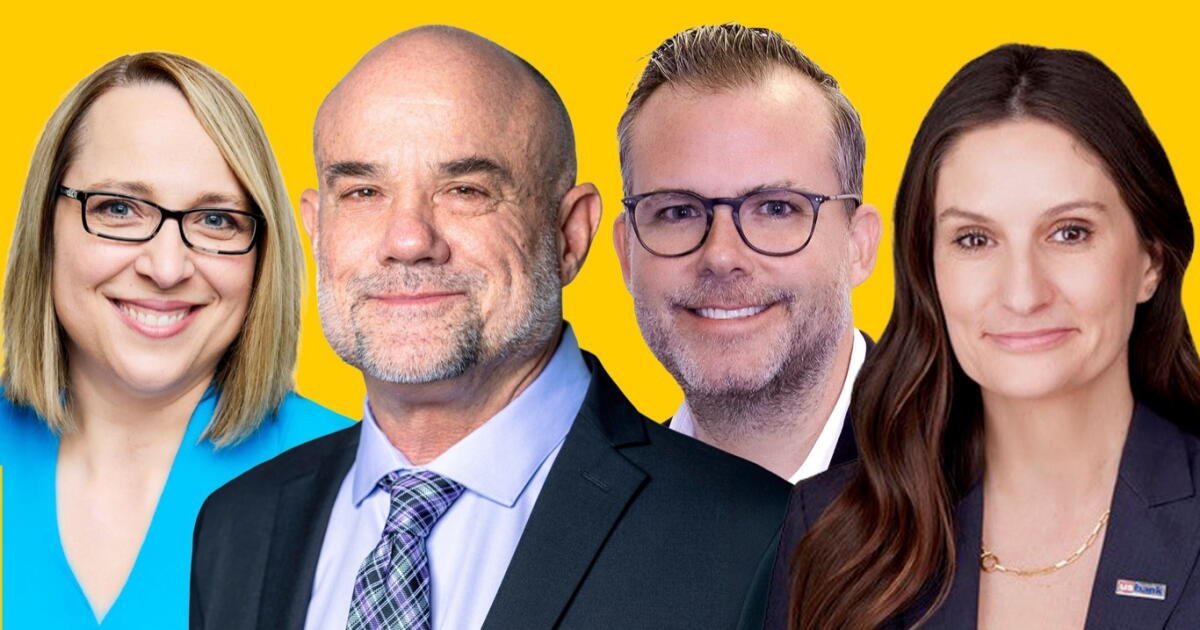
This Wealth Management & Estate Planning roundtable section is produced by the LA Times Studios team in conjunction with Axos Advisor Services; Ervin Cohen & Jessup LLP; Lagerlof, LLP; and U.S. Bank Private Wealth Management.
Ongoing market developments across multiple sectors have helped to open up new private wealth management products and services to a broader array of people and families. This, along with a surge among high-net-worth families to explore ways to better manage their finances and make plans for their estates in today’s economic environment, is an indicator of just how important the wealth management process has become.
To take a closer look at the latest trends, best practices and concerns across the wealth management landscape, we have turned to some of the region’s leading experts on the topic, who graciously weighed in for a discussion and shared insights on the state of wealth management in 2026.
Q: How would you describe the current investment environment in 2026, and what do you consider to be the best investment approach, in general terms?

Kate Phelan, California and Midwest Regional Director, Strategic Wealth Planning & Advice, U.S. Bank Private Wealth Management: Resilient economic and market fundamentals continue to support the 2026 investment environment, even amid periods of uncertainty. Consumer spending, business investment and corporate earnings remain constructive, while investors closely monitor inflation, interest rates, geopolitics and fiscal policy. In this environment, investors should focus on long-term opportunities across global equities while selectively utilizing fixed income and real assets. Although elections, policy shifts and global events can create short-term volatility, long-term results are generally driven by economic growth, earnings and innovation. We see opportunities in both equities and fixed income, with bond yields remaining attractive relative to recent years. We favor large U.S. equities, complemented by selective exposure to structured credit and global infrastructure. A diversified portfolio aligned to long-term goals remains, in our view, the most effective approach for navigating uncertainty while pursuing growth and income.
Q: What are the most critical strategies high-net-worth individuals should prioritize in today’s economic environment?

Joshua Driskell, Managing Partner, Lagerlof, LLP: Start by locking in the current, historically high gift and estate tax exemption before it shrinks – giving away appreciating assets now removes future growth from your taxable estate. Pair that with flexibility: Markets, interest rates and tax law all move, so build plans that can adapt rather than assumptions that can’t. Use trusts to shift appreciation to the next generation while retaining some control and creditor protection. Revisit your asset titling and beneficiary designations, which quietly override your will. Diversify beyond concentrated positions, and keep enough liquidity so heirs aren’t forced to sell assets at a bad time to cover taxes. Finally, coordinate your advisors – attorney, accountant and wealth manager – so strategies reinforce rather than undercut each other. The through-line is acting deliberately now while the rules remain favorable.
Q: How has estate planning changed over the past five years, and what updates should high-net-worth families make to their existing plans?

Christopher D. Carico, Partner and Co-Chair, Estate Planning, Probate and Trusts Practice, Ervin Cohen & Jessup LLP: With the federal estate tax exclusion now at $15 million per individual and $30 million per married couple, the traditional A/B family trust structure, which divides assets into a revocable survivor’s trust and an irrevocable bypass trust upon the first spouse’s death, may no longer be the most advantageous approach for many families. For married couples whose combined estate is expected to remain below $30 million, an alternative structure using a survivor’s trust and a marital deduction trust can provide significant tax advantages. This approach not only avoids federal estate tax by preserving the deceased spouse’s unused estate tax exclusion through portability, but it also allows the deceased spouse’s share of appreciated assets to receive a step-up in basis at the surviving spouse’s death. As a result, beneficiaries may substantially reduce or eliminate capital gains tax when those assets are ultimately sold.
Q: Looking ahead over the next decade, what emerging trends – from tax policy to demographics to technology – will have the greatest impact on wealth preservation and legacy planning?

Amy Morris, Senior Vice President, Strategy, Offer and Enablement, Axos Advisor Services and Axos Clearing: The biggest trend in wealth preservation is the shift from fragmented financial relationships to integrated financial planning. Investors increasingly expect their banking, lending, investing, cash management and estate planning strategies to work together rather than exist in separate silos. As financial lives become more complex, the ability to view wealth holistically is becoming a competitive advantage. We’re also seeing greater adoption of tools that expand the wealth conversation beyond traditional investments, including securities-backed lending, cash management solutions and investable health savings accounts. These aren’t necessarily new ideas, but they’re being used more strategically and in a more coordinated way. Ultimately, the future of wealth preservation isn’t about having access to more products. It’s about having a clearer view of your entire financial picture and working with professionals who can help connect the dots across it all.
Q: California doesn’t have a state estate tax, but residents still face significant tax challenges. What planning opportunities are unique to Southern California?
Phelan: To date, the state estate tax has failed to gain any steam in California, though it remains a possibility in the future. That said, tax planning is still an important, and potentially onerous, matter for California residents. California residents should be more cognizant of income-tax planning opportunities, including maximizing funding of qualified accounts, such as IRAs and 401(k)s, Health Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs). In addition, considerations regarding Propositions 13 and 19 may make inter-family real estate transfers more advantageous, particularly for the recipient, but careful planning and proper tax advice is required to get it right.
The future of wealth preservation isn’t about having access to more products. It’s about having a clearer view of your entire financial picture and working with professionals who can help connect the dots across it all.
— Amy Morris
Q: What conversations should parents be having with adult children to prepare them for inheriting wealth responsibly?
Carico: Parents should teach their children that an inheritance is a privilege, not an entitlement. Under California law, parents are generally free to leave their assets to whomever they choose, including friends and charities. While most parents intend to leave their wealth to their children, an outright inheritance can do more harm than good if it is not managed responsibly. Parents should make clear that an inheritance carries both an opportunity and an expectation that it will be used wisely. Encourage children to view themselves as stewards of family wealth, using what they need while preserving the remainder for future generations and meaningful charitable purposes.
Driskell: Start earlier and more openly than instinct suggests. Silence breeds either entitlement or anxiety, so explain not just what children may inherit but the values and effort behind it. Cover the basics of managing money – budgeting, investing and the difference between spending and preserving wealth. Introduce them to your advisors so relationships exist before they’re needed in a crisis. Be candid about your intentions, including any structures like trusts, and explain why you chose them; unexplained restrictions often feel like distrust. Discuss responsibility that comes with wealth: charitable values, stewardship and avoiding lifestyle inflation. If children will have differing roles or shares, address it directly to prevent later conflict. These aren’t one-time talks but an ongoing series that matures alongside your children. The goal is preparing capable heirs, not just transferring assets.
Phelan: Parents should begin by discussing the “why” behind their wealth, not just the amount. Adult children need to understand the family’s values, the purpose of the assets and the responsibilities that come with managing them. These conversations should cover expectations around spending, saving, investing, philanthropy and using wealth to support long-term goals. Once the “why” is clear, parents can explain the “how” and then the “what.” Understanding the reasoning behind financial decisions and how an estate plan works helps adult children better appreciate what they may inherit. Transparency about estate plans, decision-making roles and asset transfers is important, as is encouraging questions and financial education. The goal is not to create entitlement but to build confidence, financial capability and a shared sense of stewardship and purpose.
Q: What’s one financial planning move every successful executive should make before the end of this year?
Morris: One of the smartest financial planning moves an executive can make before year-end is taking a complete look at both sides of their balance sheet. Most executives know exactly what’s happening with their business cash flow, capital needs, lending relationships and liquidity before making major decisions. Yet many approach their personal finances in isolation, with investments, banking, lending and cash management spread across different providers and disconnected conversations. Before year-end is a great time to sit down with a wealth management professional and make sure they have the full picture. When your advisor understands not only your investment portfolio but also your cash flow needs, real estate holdings, business interests and existing debt, they’re better positioned to help you evaluate opportunities and tradeoffs. In my experience, wealth is often built not just through investing but through thoughtful use of leverage and liquidity. That’s why it can be valuable to work with a team that can bring together investment management, cash management, lending solutions and banking services in a coordinated way. Whether it’s a mortgage, a securities-backed line of credit, a high-yield cash strategy or financing for a business opportunity, having those conversations under one roof can lead to more informed decisions. The most successful executives tend to have a clear understanding of their entire financial picture. The end of the year is the perfect opportunity to make sure your advisory team does, too.
An estate plan should evolve as a family’s circumstances change. Major life events, financial changes and changes in the law can quickly make an existing plan outdated.
— Christopher D. Carico
Q: When does it make sense to establish a family office or outsource family office services, and what benefits do they provide?
Phelan: A family office is valuable when wealth, family structures, investments and governance needs become too complex to manage informally. Families often establish or outsource family office services after a liquidity event, during a business transition or when multiple generations, entities and advisors require coordination. Key benefits include: a) Centralized oversight of investments, tax, estate planning and reporting; b) Stronger governance, succession planning and next-generation education; c) Greater privacy, control and continuity across generations; d) Access to specialized expertise without the cost of building a full in-house team; and e) Improved efficiency through consolidated reporting, technology and coordinated service providers. For many families, outsourcing through a multi-family office provides professional services, shared expertise and cost savings without the complexity and expense of building a standalone family office. The right approach depends on the family’s wealth, complexity, desired level of control and long-term legacy objectives.
Q: What role should charitable giving and philanthropy play in a comprehensive wealth strategy, and what are the most tax-efficient ways to give?
Driskell: Philanthropy should express your values while also serving your plan; done well, it does both. The most efficient approach is giving appreciated assets – stock or property – rather than cash, since you avoid capital gains tax and still deduct the full value. Donor-advised funds let you take a deduction now, especially in a high-income year, then direct grants over time. Charitable trusts can generate income for you or your family while ultimately benefiting a cause, splitting the tax and philanthropic goals. For those over the required age, giving directly from retirement accounts satisfies mandatory withdrawals tax-free. Larger families, larger gifts and the desire for control lead families to establish a private foundation to involve multiple generations in giving. Whatever the vehicle, coordinate timing with income and estate goals. Charitable dollars reduce your taxable estate while advancing causes you care about – rarely an either/or.
Carico: Every client should ask: “How much is enough?” At some point, the marginal benefit of additional wealth to a beneficiary diminishes, while the opportunity to create a meaningful charitable legacy grows. Assets beyond a family’s needs can be directed to charity through a private foundation or, more simply, a donor-advised fund. Retirement accounts are often the ideal charitable asset because they can be subject to both estate and income taxes if left to individuals but generally pass 100% tax-free to qualified charities.
A diversified portfolio aligned to long-term goals remains, in our view, the most effective approach for navigating uncertainty while pursuing growth and income.
— Kate Phelan
Q: Artificial intelligence is changing nearly every industry. How is AI transforming wealth management, financial planning and estate administration – and where should clients still insist on human advice?
Morris: AI is transforming wealth management by helping advisors work smarter, faster and more holistically for their clients. But the most important conversations in a client’s financial life still require a human being. AI is already helping streamline research, automate administrative tasks, identify opportunities and surface insights that might otherwise go unnoticed. Done well, it allows advisors to spend less time gathering information and more time engaging with the people they serve. What’s interesting is that as technology becomes more powerful, the advisor’s role becomes more important, not less. For years, wealth management conversations were often centered on the portfolio. Today, clients want guidance that extends far beyond investments. They want help thinking through liquidity needs, lending strategies, cash management, business ownership, retirement, family goals and major life decisions. AI can provide analysis. It can identify patterns. It can help connect information across a client’s financial life. What it cannot do is understand the personal context behind those decisions or help a client navigate competing priorities and emotions. Those are fundamentally human conversations. The future of wealth management isn’t human versus AI. It’s human expertise enhanced by AI. The advisors who will create the most value are those who use technology to develop a more complete understanding of their clients and bring together all aspects of their financial lives into a single conversation. When that happens, advice becomes more personal, more relevant and ultimately more impactful.
Phelan: Artificial intelligence is making wealth management, financial planning and estate administration more efficient by helping advisors analyze data, model scenarios, summarize complex documents and streamline administrative work. It also enables more holistic views of a client’s financial life, bringing together banking, investments, planning and estate information to support more personalized guidance. AI can help surface insights and simplify complexity, but it doesn’t replace human judgment. When decisions involve family dynamics, major life transitions, estate intentions, risk tolerance or long-term financial goals, clients should insist on human advice. The most effective model is one in which AI handles routine tasks and information synthesis, while advisors focus on what technology cannot: building trust, understanding context, navigating nuance and helping clients make confident decisions.
Q: How can families protect themselves from lawsuits, identity theft, cybercrime, financial elder abuse and other risks that increasingly target affluent individuals?
Morris: As wealth grows, so does visibility, and that can make affluent families attractive targets for everything from identity theft to sophisticated cybercrime. While no one can eliminate risk entirely, simple habits can make a meaningful difference, such as enabling multi-factor authentication, monitoring accounts regularly and being cautious about unexpected emails, texts or requests for sensitive information. Beyond personal vigilance, families should consider the strength of the institutions helping safeguard their assets and data. Security today is not just about technology. It is about having the right people, processes and oversight behind the scenes. We often remind wealth management firms that cybersecurity is really a shared responsibility. The most effective protection comes when clients, advisors and financial institutions work together. That partnership creates multiple layers of defense and helps families stay ahead of threats before they become problems.
Carico: Simple planning steps can significantly reduce the risk of lawsuits, creditor claims, financial exploitation and other threats to family wealth: a) Hold investment real estate, businesses and other high-liability assets in LLCs, limited partnerships or corporations to help shield personal assets; b) Maintain a substantial umbrella liability insurance policy, particularly as driving and other liability risks increase with age; c) Consider leaving assets to a surviving spouse in a QTIP trust, rather than outright, to protect them from creditors and financial predators; d) Keep significant investment accounts with trusted fiduciary financial advisors who can help identify and prevent suspicious transactions; e) Leave a portion of a child’s inheritance in a creditor-protected irrevocable trust to preserve assets from future claims; and f) For elderly clients, consider naming a trusted adult child as a co-trustee to help safeguard the family home from fraud, undue influence or imprudent transfers.
Markets, interest rates and tax law all move, so build plans that can adapt rather than assumptions that can’t.
— Joshua Driskell
Q: If someone hasn’t reviewed their estate plan in five or ten years, what are the top reasons they should revisit it now?
Phelan: If you haven’t reviewed your estate plan in five or 10 years, it’s worth revisiting because both your life and the world around you may have changed. Major life events such as marriage, divorce, the birth of children or grandchildren, a death in the family or changes in relationships can all affect whether your plan still reflects your wishes. Changes in tax laws or estate planning regulations may also create new opportunities or risks. Just as important, an older plan may no longer align with your current goals, family dynamics or legacy intentions. Estate planning is about more than transferring assets. It includes decisions about healthcare, guardianship, powers of attorney, philanthropy and how you want your family supported and informed. A good rule of thumb is to review your plan every three to five years or sooner if a significant life event occurs.
Driskell: Tax law has changed – exemptions and thresholds today likely differ from when you signed, and your plan may no longer be optimized or even accurate. Life has changed too: marriages, divorces, births, deaths and new assets can leave beneficiaries, guardians or executors outdated or inappropriate. Your net worth has probably grown, potentially exposing your estate to taxes the old plan never anticipated. The people you named as trustees or agents may no longer be the right choices. Documents like powers of attorney and health directives can become stale, and institutions may resist honoring old ones. Digital assets you now own may not be addressed at all. Finally, your goals evolve. A plan is a snapshot of one moment; a decade later, it may no longer reflect your life, your wealth or the law.
Carico: An estate plan should evolve as a family’s circumstances change. Major life events, financial changes and changes in the law can quickly make an existing plan outdated. Clients should review their estate plan every five to ten years, or sooner following significant events, including: a) Marriage, remarriage, divorce or the birth of a child or grandchild; b) The death, disability or incapacity of a named fiduciary or beneficiary; c) A significant increase in wealth, receipt of an inheritance, sale of a business or other major liquidity event; d) A move into or out of California or changes in immigration status; e) A beneficiary developing special needs, receiving government benefits, entering a high-liability profession or joining the family business; and f) The onset of cognitive impairment, long-term care needs, family estrangement or other material changes affecting the family or its assets.
Q: What’s the most common misconception people have about trusts?
Driskell: That they exist only to reduce taxes. Trusts can absolutely help save on taxes, and for many families they do – but that is one benefit among several, not the whole purpose. At their core, trusts are tools for control, protection and a smooth transfer of wealth. They let you decide how and when assets reach beneficiaries – valuable for young children, heirs who need guardrails or a loved one with special needs. They keep your affairs private and spare your family the public, often slow, court process a will alone requires. They can shield assets from creditors or divorce and provide for management if you become incapacitated. The other common misconception is that signing the trust finishes the job; assets must actually be moved into it to work. A trust is ultimately a flexible framework for stewardship.
Phelan: One of the biggest misconceptions is that trusts are only for the very wealthy. In reality, trusts can be valuable for families at many wealth levels because they help ensure your wishes are carried out, provide a framework for managing assets and can make things easier for loved ones during difficult times. Another common misunderstanding is that creating a trust is a “one-and-done” exercise. Trusts and estate plans should be reviewed periodically as families, assets and laws change. People also often assume a trust is just about money. In practice, it can play a much broader role in supporting family goals, reducing confusion, clarifying responsibilities and helping avoid unnecessary conflict. Ultimately, a trust is less about wealth and more about creating a clear plan that reflects your wishes and protects the people you care about most.
Morris: The biggest misconception about trusts is that they’re only relevant once you’ve accumulated significant wealth. In reality, trusts are often about organization, continuity and family goals as much as they are about assets. Many people mistakenly view a trust as a standalone legal document rather than part of a broader financial strategy. The most successful outcomes happen when trust planning is integrated with the rest of a family’s financial life, including investments, banking relationships, liquidity needs and estate objectives. As financial lives become more complex, coordination becomes increasingly important. That’s where financial advisors can play a unique role. They sit at the intersection of the various professionals supporting a family, whether that’s attorneys, tax professionals, trustees, bankers or other specialists. While each has a specific area of expertise, the advisor often has the most complete view of the client’s overall financial picture. The real value isn’t simply having a trust in place. It’s ensuring that everyone involved is working from the same playbook and that the trust aligns with the family’s broader financial goals. In many cases, that coordination is what turns a good estate plan into a great one.
Carico: There are several common myths. One is that a revocable trust is self-executing after the first spouse’s death. The reality is that the surviving spouse should promptly consult an estate planning attorney. Trust administration often requires legal, tax and fiduciary actions, particularly when children or other beneficiaries have protected interests. Another myth is that a revocable (living) trust eliminates all estate taxes. In reality, neither a revocable trust nor a will eliminates all estate taxes for individuals and couples where the estate exceeds the federal estate tax exclusion amount of $15,000,000 and $30,000,000, respectively. Both can be structured to defer and minimize estate taxes, but the primary advantage of a revocable trust over a will is avoiding probate. Yet another myth is that a revocable trust protects your assets from creditors. The reality is that because you retain control over a revocable trust, its assets generally remain reachable by your creditors. While properly drafted trusts can protect a spouse or other beneficiary’s inheritance from their creditors, California law does not permit self-settled asset protection trusts. Clients seeking that type of protection must generally look to jurisdictions such as Nevada, Delaware, Alaska, Tennessee, South Dakota and other states that have special legislation approving domestic asset protection trusts.
Q: Is there a wealth strategy that affluent families consistently overlook?
Driskell: Planning for the transfer of knowledge and values, not just assets. Families pour energy into tax structures and investment returns, then leave heirs unprepared to receive what’s coming – which is why inherited wealth so often erodes within a generation or two. The overlooked work is governance: regular family meetings, a shared statement of values, clear roles and gradually involving the next generation in decisions. Closely related is neglecting liquidity planning – families rich in illiquid assets like real estate or a business can face a tax bill with no easy way to pay it, forcing rushed sales. Also commonly missed: coordinating beneficiary designations and titling with the overall plan, since these quietly control large sums. The assets usually get attention. The human infrastructure that lets those assets survive and serve the family rarely does.
Q: If you could give every business owner one piece of advice about protecting their legacy, what would it be?
Carico: Discuss your succession plan with your children before a health crisis arises. Explain who will inherit the family business, why that decision was made and how other children will be treated fairly through the distribution of other assets. If these conversations are difficult, consider involving a mediator, family counselor or psychologist to facilitate them. When the business represents most of the family’s wealth and only one child will inherit it, consider using life insurance that is owned by the children (either outright or in trust) to achieve a more equitable overall distribution.