Unlock the Editor’s Digest for free
Roula Khalaf, Editor of the FT, selects her favourite stories in this weekly newsletter.
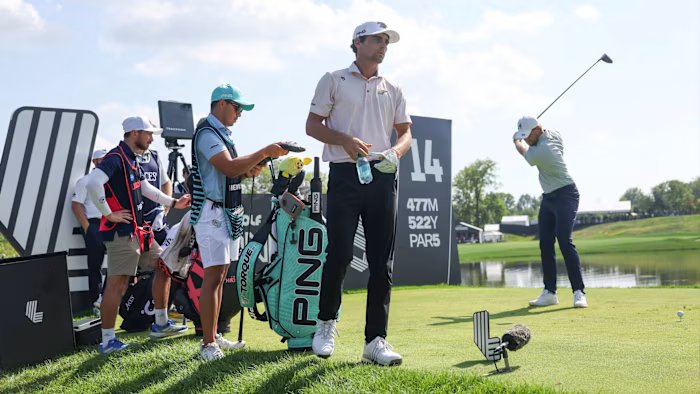
The private equity firm that has struck a preliminary deal to save LIV Golf is set to commit up to $10mn to help fund the league’s US bankruptcy in an effort to allay concerns that it is not serious about relaunching the upstart golf tour.
When LIV entered bankruptcy on September 8, it trumpeted a rescue deal with BC Partners that included a commitment from the firm to invest $300mn post-bankruptcy to finance a “LIV 2.0” circuit debuting in 2027.
But BC Partners and LIV have since clashed with the Public Investment Fund of Saudi Arabia, which this year withdrew its vast backing for LIV. People involved in the talks said that LIV collapsed with $400mn in gross obligations to players.
The PIF, which has committed $50mn in bankruptcy financing, has expressed concern to LIV management that BC Partners’ primary motivation for the deal is to acquire LIV’s $5bn of net operating losses.
These cumulative losses can be used to offset future taxable income, creating the firepower to buy new businesses — a strategy that BC Partners has successfully deployed in other investments.
The fresh $10mn loan from BC Partners is, in part, to allay scepticism from PIF about the sincerity of the private equity firm’s interest in LIV 2.0.
“PIF is not going to sell a corporate shell to a hedge fund,” according to one person involved in the talks, who said the sovereign wealth fund wanted BC Partners to be serious about continuing with golf tournaments.
Outstanding debts to star players including Jon Rahm and Bryson DeChambeau represent a further hurdle to rebooting the league. People close to LIV and BC Partners described talks with players as “constructive”.
According to court filings, the BC Partners deal terms required that a court motion approving its agreement for “LIV 2.0” be filed within three days of the September 8 federal bankruptcy petition and that a hearing to approve that agreement take place within 10 days. None of this has occurred.
People familiar with the matter said that LIV, PIF and BC Partners have in recent days been locked in intense negotiations to find a way to navigate through the Chapter 11 process.
PIF’s bankruptcy financing requires a plan of reorganisation to be filed by LIV Golf within 30 days of the bankruptcy filing and that without the three sides reaching a definitive deal, the case would shift to “an orderly wind-down”.
“The BC 2.0 deal is not committed,” said a person close to PIF. The person said PIF believed LIV had been too aggressive in selling the feasibility of BC Partners closing a transaction that was agreeable to the Saudi fund.
PIF has, however, agreed for now to allow BC Partners to keep working with LIV and its golfers to explore a revamped league.
Among the points of contention between the sides has been BC Partners’ request that its mooted bankruptcy loan be secured by some of the tax-loss assets. The $10mn loan, which could be later augmented, is expected to fund hiring and start-up costs for the 2027 season while the $50mn from PIF is allocated for shutdown costs of the legacy league.
BC Partners was selected by LIV as its new backer due to its stated interest in continuing with a slimmed-down global golf league, according to people familiar with the matter, who added that Oaktree Capital, Ares Management and Apollo Global Management had all previously conducted due diligence on LIV.
Court filings show that LIV players are being offered equity in the new league as payment for their outstanding debts and that they will be eligible for further payouts should they choose to keep playing with LIV.
LIV has filed a motion with the court seeking permission to terminate existing player contracts, claiming they “do not reflect the contemplated compensation structure under LIV 2.0”.
Players have been largely quiet since the bankruptcy filing. However, DeChambeau and the Australian golfer Cameron Smith have each hired US law firms to represent them, according to bankruptcy court filings.
A committee of unsecured creditors, which may include LIV players, will be approved by the bankruptcy court within weeks. The group could then pursue claims against LIV and PIF, the latter of which owned 98.5 per cent of the league going into bankruptcy.
PIF, which has spent $5.5bn on LIV since its 2021 inception, is seeking liability releases from players and trade vendors as part of any final LIV bankruptcy exit.