Alex Fielding, co-founder and CEO of Privateer, writes for Splash today, discussing insurance and GPS spoofing.
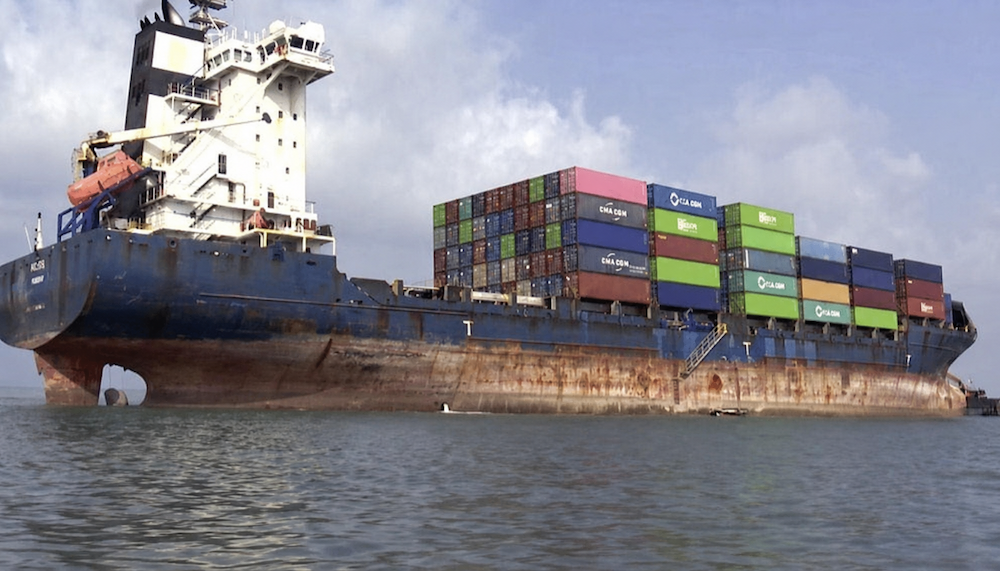
Last year, a tanker owner reportedly spent 45 days with its bank transactions frozen after its broadcast position jumped from Fujairah to Iran’s Kharg Island, triggering US sanctions scrutiny. The ship never went to Iran. Its reported position said otherwise, and everything downstream believed it.
This is no outlier. Around 400 ships a month experienced satellite navigation interference in 2025. By the first day of the 2026 Iran conflict, that figure had reached nearly 1,100 ships.
Marine war risk insurance depends on knowing where vessels operate. For two decades, the Automatic Identification System (AIS), which commonly draws positioning data from GPS, has been central to that assessment. Yet the Joint War Committee has redrawn its Listed Areas three times this year, expanding areas where vessel movements affect insurance obligations and costs, precisely as satellite navigation interference makes those movements harder to verify.
More of the map depends on position, and position is getting harder to prove.
Spoofing was once associated primarily with shadow fleets. Now it is increasingly a consequence of conflict. States jam and spoof navigation signals to counter drones and missiles, inadvertently affecting commercial shipping. Jamming disrupts positioning; spoofing creates false coordinates that can propagate through AIS.
The consequences extend beyond navigation. False positions can suggest entry into sanctioned ports or war risk areas, triggering compliance investigations, banking delays and insurance disputes. Compromised records can also complicate collision, grounding and claims investigations. Owners may find themselves defending movements their vessels never made.
For insurers and vessel owners, the answer is not simply accommodating unreliable data. It is strengthening location intelligence through independent verification, systematically incorporated throughout the insurance relationship.
Four practical changes can make that possible.
First, establish a vessel’s behavioural history before underwriting. Beyond standard due diligence and declared routes, underwriters should assess historical AIS gaps, identity changes, port calls and ship-to-ship transfer patterns. This provides a more complete risk profile and supports premiums reflecting demonstrated behaviour rather than assumptions.
Second, independently verify movements in high-risk waters. Commercial satellite imagery, including radar capable of observing through darkness and cloud, can corroborate vessel locations. Radio-frequency detection can help identify ships operating without AIS, using emissions from onboard radar and communications equipment.
Neither source is definitive alone. Identifying a particular vessel from satellite observations requires careful analysis. But corroboration across independent sources creates stronger, defensible evidence.
Third, establish clear investigation triggers. Physically impossible AIS tracks, unexpected position changes in interference zones, unexplained reporting gaps, suspected sanctioned-vessel encounters or discrepancies between reported movements and satellite observations should prompt scrutiny.
These indicators are not proof of wrongdoing. They should initiate proportionate review supported by documented evidence, not automatic penalties.
Fourth, share responsibility for location integrity. Verification benefits policyholders as much as insurers. Assured positioning, navigation and timing systems can improve onboard location reliability and document interference. High-definition video can support operational alerts, while satellite and radio-frequency observations provide external corroboration.
Together, these capabilities strengthen situational awareness during transit and provide evidence for underwriting, incident investigations and claims.
None of this requires inventing new technology. Navies, coast guards, sanctions investigators and commodity traders already cross-check AIS against independent observations. Marine insurers increasingly have access to comparable capabilities. The opportunity is to make verification routine rather than exceptional.
There is also a commercial incentive. Vessel owners investing in reliable positioning technologies could receive preferential insurance terms. Earlier this year, a war risk mutual announced premium discounts for members installing assured positioning receivers, demonstrating how location integrity can become a measurable factor in pricing.
That approach creates mutual value: owners gain operational resilience and stronger protection against false accusations, while insurers gain better information for evaluating exposure, monitoring risk and resolving claims.
Without it, the industry faces an uncomfortable trajectory. The Joint War Committee is drawing more boundaries in waters where GPS interference is increasingly prevalent. The result is a growing population of legitimate vessels whose electronic records may suggest movements they never made.
For owners, this creates financial and reputational exposure. For insurers, it introduces uncertainty into underwriting decisions and claims assessments. Independent verification cannot eliminate conflict-related risk, but it can distinguish unreliable reporting from actual vessel behaviour.
Drawing the lines is the Joint War Committee’s responsibility. Establishing whether a vessel actually crossed them falls to operators and insurers.
In increasingly contested waters, a reported position alone is no longer sufficient. Knowing where a vessel was should not be a matter of uncertainty. It should be a matter of evidence.