Workspace Group has recorded a £121.2m loss before tax for the first six months of the year and deferred a decision on its interim dividend despite “good early signs” in the turnaround of the flexible office firm.
The group’s loss increased by 70.4% versus H1 2025, as previously guided, which was driven by a 6.6% fall in its property portfolio value from £2.13bn to £1.96bn.
However, the group said it was “excited” about the strategic progress it has achieved in delivering its turnaround strategy set out in June. Tom Edwards-Moss, CFO of Workspace, told Property Week it was “still early days in our transformation of the business”.
“We’re really encouraged and excited about where we are, and there’s a real distinction to be made between our theoretical performance and the strategic progress we’re making. We’re showing good initial signs of progress, but it will take time for that to feed through into actual results.
Net rental income fell 10.9% from £58.7m to £52.3m following a number of disposals, but the firm pointed to progress from its new all-inclusive pricing model which was resulting in a 6% uplift in rents across its unfurnished products.
Circa 491 lettings and 219 renewals worth a combined £20.6m have been completed year-to-date, down from 604 lettings and 236 renewals worth £21.6m last year, reflecting “a quieter market” and transition within the company.
Its stabilised portfolio occupancy stood at 82.8% as of 30 September, up marginally. EPRA net tangible assets per share fell 11.9% to £6.05 from £6.87.
The firm is making progress towards its disposals target of £200m by March 2027, with three disposals worth £12.6m since March 2026 boosted by an £16m in new deals this quarter. A further £48m is under offer and a further £180m is in active discussion.
Edwards-Moss added: “We’ve been working hard on disposals, it is just a slow market at the moment so it takes time for the results of that to be seen. Its important that we maintain our discipline on disposals.”
He described the outcome of the firm’s general meeting in July, where shareholders overwhelming backed the board’s strategy over proposals from activist investor Saba Capital, as an “external validation” of the firm’s own discussions with shareholders. “The outcome gave us a lot of confidence that was have the support of shareholders. We’re comfortable with where we are.”
He added that with a lot of debt maturing over the next 18 months and with uncertainty in the bond markets, the firm had decided to defer a decision on its interim dividend to the full-year results where the firm would have better visibility.
Charlie Green, chief executive officer, added: “We are in a period of transition as we reshape our offer and transform the business. The board remains focused on disciplined capital allocation, including continuing to invest in the existing portfolio to drive rental growth.”
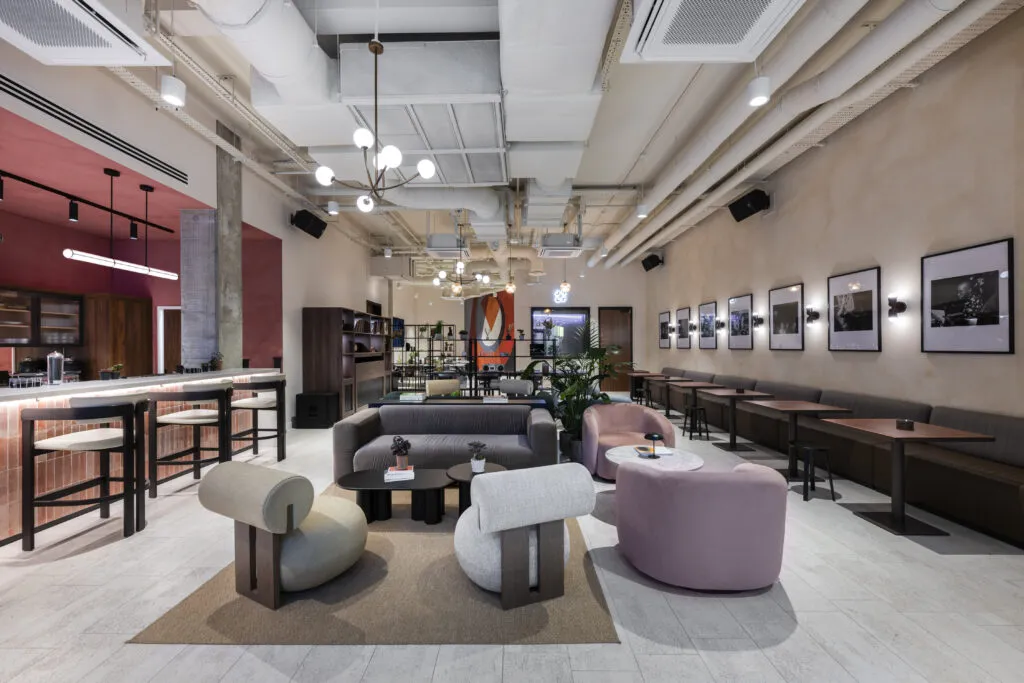
Workspace owns and manages 3.7m sq ft of flexible space across 50+ locations in the London area.